
AI & the new ‘new economy’
Respected futurist Paul Saffo argues you should look back twice as far as you look forward, particularly if you are seeking to understand big shifts.
In 2017 I wrote: “It’s official: the new economy won”. It highlighted the shift to the ‘new economy’ that crystalised in 2016. In the decade prior the largest companies by market capitalisation were dominated by ‘old economy’ firms: Exxon; GE; Total; and Citi. Exxon, GE and Total were classic pipeline businesses: input; transform; output. At #4 Microsoft filled out the top 5. The combined market cap of the top 5 was ca. $1.7 T.
By 2016 it was Apple; Alphabet; Microsoft; Amazon; and Facebook. A shift in market structures with a combined market cap of $2.3T: a modest 3% CAGR. I lazily referred to them as internet companies, but that’s only part of the story. In reality, the newcomers’ dominance was attributable to their platform business models, built on a substrate that allowed real time network effects. Microsoft was also a platform business but built on the economics of ‘increasing returns’: embedded software and high switching costs that allowed the dominance of an inferior product.
Ten years later the top 5 firms by market capitalisation are now: Nvidia; Apple; Alphabet; Microsoft; and Amazon.
Table 1: Market Capitalization (US$B)
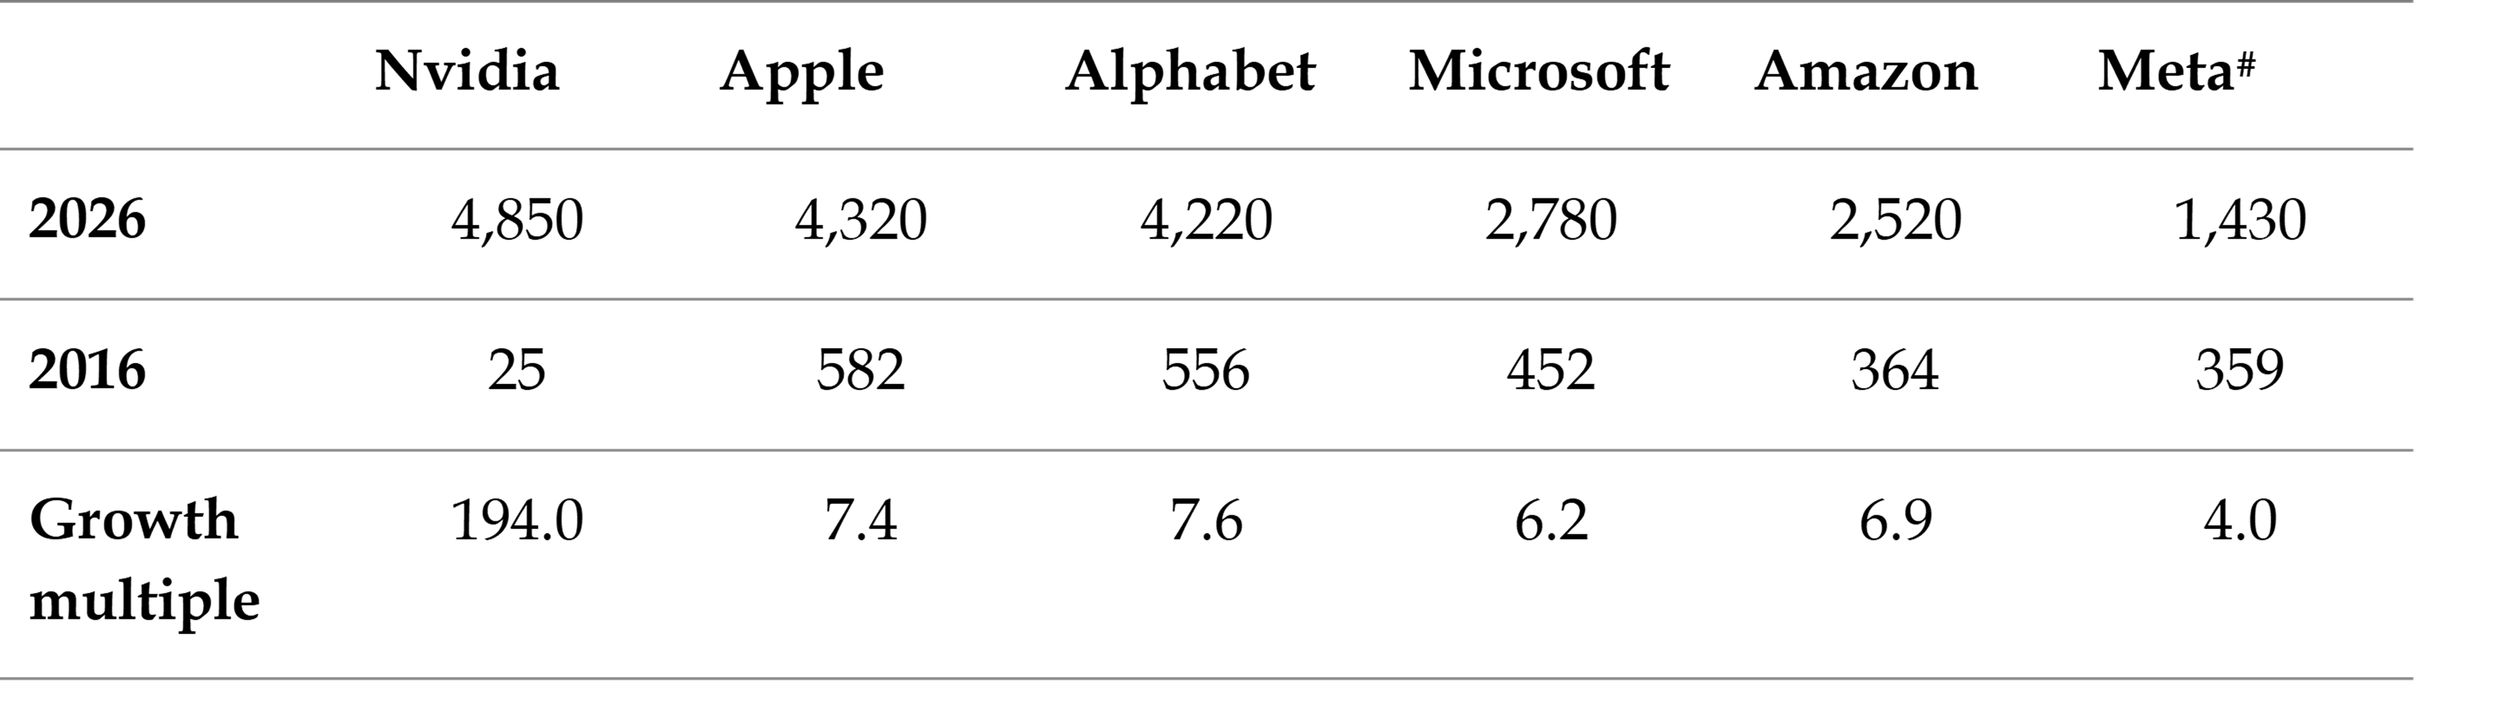
# Numbers are indicative only. They can vary significantly over relatively short periods of time.
## Nvidia was nowhere near top 5 in 2016. Meta (Facebook) ranked #5 in the 2016 largest companies by market cap. Today it is ranked #12
Nvidia is the clear outlier. Its market cap has risen 194x: a 69% CAGR. By contrast, the other four have averaged a 7x growth: a 21% CAGR.
Nvidia is a bet on the ‘picks and shovels’ of the AI surge.
Microsoft and Google are the Develop Global – a contract miner that also bets on its own ore bodies – of the AI boom. They are renting the infrastructure (compute), and at the same time betting on the upside from direct services (Copilot; Open AI investment; Gemini).
The metaphor for Apple is a little harder to land. It is essentially betting people just want AI to show up on a platform they trust. No big bets on the infrastructure; no stand alone AI model.
Let’s situate these shifts on a timeline.
The internet was opened to commercial traffic around the mid 90’s. This was followed by a speculative bubble that collapsed with the dot com crash through the early 2000’s. But this was also the era when the internet transitioned from financial exuberance to the real economy.
The early years of adoption of the internet by incumbent firms were experimental as they sought to understand what might be possible. Beyond the early adoption by traditional businesses, we saw the emergence of new businesses, bringing new products and services to the real economy.
By 2016 the ‘internet economy’ had matured. Think of it as a 50 year old. Not yet quite peaked perhaps, but not much upside left for most. … DDB
This is a pattern that repeats across multiple techno-economic paradigm shifts. Financiers sense an opportunity to make outsize returns, and money piles into the new. This grows to a frenzy, despite many of the investments failing. Inevitably it leads to over-investment and a bust. During this phase, much of the capital goes into infrastructure.
In the meantime, incumbent firms start to explore the potential of the new paradigm: often piecemeal and uneconomic. But no-one wants to be left behind. It ultimately leads to capital invested to make existing businesses more efficient: a more predictable pathway. Incumbents work out how to deploy the new technology for business to generate economic returns.
Where are we in 2026?
Financial capital is being invested at what can only be described as a frenzy. When it collapses is anyone’s guess, but the theory is quite clear: collapse seems likely.
There are some who continue to suggest ‘this time is different’. According to the AFR:
Wendy Cromwell, Vice Chair of US funds management giant Wellington Management, thinks comparisons [with the dot com boom of the internet] are wide of the mark … she sees a better parallel in the China boom”
( James Thomson: 4 Sep 2026)
Despite its economic success, I’m not sure China is an exemplar for efficient capital allocation.
Incumbent companies are running various pilots, as we saw in the internet boom: uncertain how it will play out, but conscious that they must work through this learning phase. The early-stage feedback suggests so far not many of these pilots are delivering results. But who wants to be a laggard?
How will it ultimately play out? In a provocative article post the dot com bust, one analyst remarked:
It may take an extended period of watching before we start to understand the real impact of the net on business … Patrick Marren (2003). Back to the Old Rules
What will you do while you watch to understand the real impact of AI on business?
One thing you can do is invest in deeper conversations about the potential impact of an AI collapse. Look beyond the surface impacts. Consider the second and third order impacts. How will your business stand up to the rupture such an event would inevitably create? What opportunities might emerge?
“In the fields of observation, chance favours only the prepared mind” … Louis Pasteur